HSBC's Hong Kong Profit Rises 8% as Bad Property Loans Shrink to US$5.6 Billion
Impaired commercial real estate loans fell again in the third quarter, but HSBC is setting aside more against them as collateral values slide.
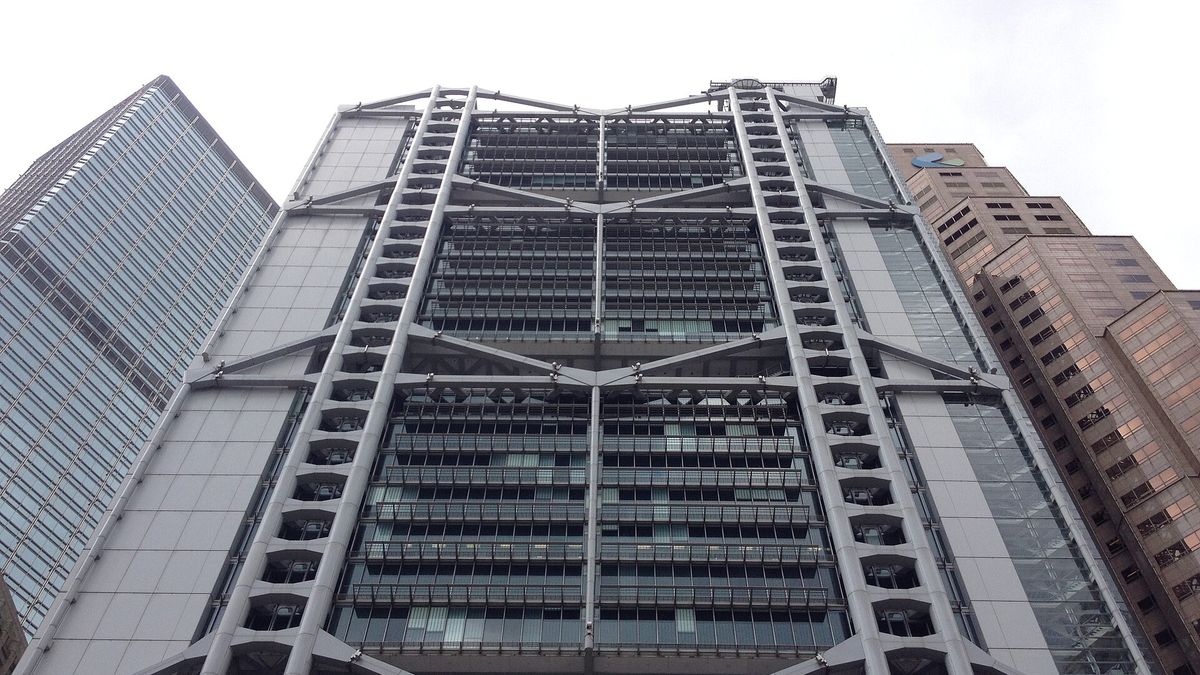
What to know
- HSBC's Hong Kong business earned US$2.57 billion before tax in the third quarter, up 8% at constant currency, on 6% higher revenue.
- Credit-impaired Hong Kong commercial real estate loans fell to US$5.6 billion at Sept. 30 from US$6 billion in June, while allowances against them rose to US$1.4 billion.
- HSBC bought back about 16.9 million shares in Hong Kong in its last US$1 billion program and plans another of up to US$1 billion by full-year results.
HONG KONG
HSBC Holdings' Hong Kong business lifted third-quarter pre-tax profit 8% to US$2.57 billion at constant currency, as deposit growth offset tighter margins and the bank booked smaller losses on the city's troubled commercial property loans.
The figures, in the earnings release HSBC filed on Oct. 27, matter for Hong Kong investors because the city is the group's profit engine and the main home of its share buybacks. They also offer the clearest read yet on whether the commercial real estate slump that hit Hong Kong lenders over the past two years is easing. The answer from HSBC's books: the stock of bad loans is falling, but the collateral behind them is still losing value.
Revenue in the Hong Kong segment, which includes Hang Seng Bank, fully owned since HSBC completed its privatization in January, rose 6% to US$4.1 billion in the quarter. Banking net interest income climbed 8% to US$3.08 billion, which HSBC put down to deposit growth, partly offset by thinner margins on time deposits as banks competed for savers' money. Wealth fees rose 7% to US$687 million. Operating expenses rose 7% to US$1.28 billion on technology spending and inflation.
Hong Kong Commercial Real Estate Loans
HSBC's Hong Kong commercial real estate book, excluding loans to mainland Chinese borrowers, shrank to US$28.9 billion at Sept. 30 from US$29.3 billion at the end of June and US$30.6 billion at the end of 2025, the bank's disclosure table showed.
Credit-impaired loans in that book fell to US$5.59 billion from US$5.99 billion in June and US$6.31 billion in December. Loans graded sub-standard or credit-impaired together dropped to US$8.1 billion from US$8.5 billion, and 95% of them were secured, the bank said.
The bank still added to reserves. Allowances for expected credit losses on the portfolio rose to US$1.41 billion from US$1.33 billion in June and US$1.08 billion at the end of last year. HSBC said the extra provisions reflected continued pressure on property prices, mostly in non-prime segments. The weighted average loan-to-value ratio on credit-impaired exposures reached 83% at Aug. 31, up from 82% in June and 71% at the end of 2025, meaning the buildings securing those loans are worth less relative to the debt.
There were better signs at the top of the market. HSBC said leasing improved in prime office and retail property in the quarter, and loans rated "strong" rose to US$4.7 billion from US$3.5 billion in June. Non-prime properties still face higher vacancy and weak investor demand, the bank said. Recent deals bear that out: Link REIT agreed to sell Mong Kok's 700 Nathan Road at 61% below its 2016 price.
Stage 3 charges tied to Hong Kong commercial real estate fell by US$100 million from a year earlier, helping cut the segment's expected credit losses to US$248 million from US$302 million. Over nine months, the group booked US$300 million of charges covering Hong Kong commercial real estate and allowances for uncertainty from the Middle East conflict, without splitting the two. HSBC warned the portfolio "remains sensitive to further interest rate increases," particularly for smaller, more leveraged borrowers.
Deposits Pour Into HSBC Hong Kong
Customer accounts in the Hong Kong business grew by US$20.6 billion in the quarter at constant currency, mainly into term deposits, while customer lending rose by US$6.7 billion, helped by higher retail balances and an accounting reclassification of some wealth-related loans. The shift into term deposits mirrors the wider market: Hong Kong dollar time deposits across the banking system were 15.1% higher than a year earlier at the end of September, according to HKMA data.
For the first nine months, the Hong Kong segment earned US$7.7 billion before tax, up 12%, and its annualized return on tangible equity was 43.3%, compared with 33.9% a year earlier. Expected credit losses for the period fell by US$400 million to US$800 million, mainly on lower property-related charges.
The Hongkong and Shanghai Banking Corp., the group's Asian subsidiary, which also covers markets beyond the city, earned US$18.78 billion before tax in nine months, up 26.6%, or about 65% of the group total, The Standard reported. Its third-quarter pre-tax profit rose about 8% to US$5.89 billion, the newspaper said.
Buybacks and Capital
HSBC completed its previous buyback of up to US$1 billion on Sept. 28, repurchasing 16,921,600 shares on the Hong Kong exchange and 31,735,502 in London for cancellation. It plans a new program of up to US$1 billion, to start shortly after the results and finish by the time it reports full-year earnings. The board also declared a third interim dividend of 10 U.S. cents a share.
The group's common equity tier 1 ratio slipped to 13.9% from 14.1% in June, which HSBC attributed partly to higher risk-weighted assets and the impact of the earlier buyback. Group pre-tax profit rose 32% to US$9.6 billion, just below a US$9.7 billion company-compiled estimate, Teleborsa reported.
The Hang Seng Bank deal is starting to pay off on costs: HSBC said privatization synergies account for US$300 million of the US$1.8 billion in savings it plans to redeploy into growth areas over the medium term. Its next test is full-year results, when the new buyback is due to be complete and investors will see whether loan-to-value ratios on impaired Hong Kong property loans keep rising.
Sources
- HSBC Holdings via U.S. SEC: HSBC Holdings plc Earnings Release 3Q26 (Form 6-K) (Oct. 27, 2026)
- The Standard: The Hongkong and Shanghai Banking Corporation profit up 27pc for first three quarters (Oct. 27, 2026)
- Teleborsa via Borsa Italiana: HSBC, conti sotto le attese ma conferma previsioni e rinnova buy-back da 1 miliardo di dollari (Oct. 27, 2026)
Our standards: Capital Times reports under the principles set out in our Editorial Standards and Ethics Policy. Spotted an error? Report it to our editors.